Balancing Financial Goals When You Earn Unequally
27 September 2026
Money is rarely a neutral topic in a relationship, and it becomes even more charged when two people earn very different amounts. One partner might bring home six figures while the other earns a modest salary, or one might work full time while the other studies, raises children, or builds a business that has not yet turned a profit. Whatever the reason, unequal income does not automatically mean an unequal partnership. It does, however, mean you need a deliberate system for handling money together.
This article is for couples who want to build a shared financial life without letting income differences create resentment, guilt, or quiet power struggles. The advice here applies whether you are newly married, living together, or ten years into a relationship where the income gap has shifted over time.
Why Unequal Income Feels So Complicated
When two people earn similar amounts, splitting expenses is simple arithmetic. When incomes diverge, the math is easy but the emotions are not. The higher earner may feel burdened, wondering why they carry more of the load. The lower earner may feel dependent, embarrassed, or afraid to spend money on themselves. Both may avoid the conversation entirely, which is how resentment quietly builds.There is also a practical layer. If one partner earns far more, decisions about housing, vacations, and even groceries start to reflect that person's preferences. The lower earner might feel they have less say in big choices because they contribute less cash. That dynamic can erode a relationship faster than any single financial mistake.
The good news is that unequal income is not a problem to solve. It is a condition to manage. Couples who handle it well tend to follow a few consistent principles, and those principles are what this article will unpack.
Start With Values, Not Numbers
Before you decide who pays for what, you need to agree on what money is for. This sounds abstract, but it drives every practical decision that follows. A couple who values early retirement will allocate money very differently from a couple who values travel, a large home, or supporting extended family.Try this exercise. Each partner writes down three things they want money to accomplish in the next five years. Then compare lists. You will likely find overlap, and you will likely find friction. The overlap becomes your shared priorities. The friction becomes the subject of negotiation.
Why does this matter when income is unequal? Because if the higher earner assumes the shared goal is a bigger house while the lower earner assumes it is paying off student loans, every budgeting conversation will feel like a fight about control rather than a plan for the future. Values alignment turns money talks from conflict into collaboration.
The Trap of Assuming You Know What Your Partner Wants
Many couples skip this step because they think they already know each other. They do not. A partner who grew up with financial insecurity may prioritize a large emergency fund above everything else. A partner who grew up comfortable may see that same fund as excessive and want to invest aggressively instead. Neither is wrong. But without naming these instincts, you will keep colliding over the same decisions.
The Four Main Models for Splitting Money
There is no single correct way to divide finances when incomes differ. There are four common models, and each has real trade-offs. The right choice depends on your values, your legal situation, and how much transparency you both want.Model 1: Fifty Fifty Split
Each partner pays half of every shared expense regardless of income. This is the simplest model and it feels fair in a formal sense. It works well when incomes are close, when the relationship is relatively new, or when both partners strongly value independence.The downside is obvious when incomes are far apart. If one partner earns 200,000 dollars and the other earns 50,000 dollars, a fifty fifty split on rent, utilities, and vacations can leave the lower earner with almost nothing for savings or personal spending. Over time, that imbalance breeds resentment or forces the lower earner into debt. This model is best used when the income gap is small or when the couple has explicitly agreed to keep finances separate for other reasons.
Model 2: Proportional Contribution
Each partner contributes to shared expenses in proportion to their income. If one partner earns 70 percent of the household income, they cover 70 percent of shared costs. This is often called the fairness model, and for many couples it is the most workable.Here is how it looks in practice. Suppose the household earns 150,000 dollars total. One partner earns 100,000 dollars and the other earns 50,000 dollars. Shared monthly expenses are 6,000 dollars. The higher earner contributes 4,000 dollars and the lower earner contributes 2,000 dollars. Each person keeps the same percentage of their income for personal use, which preserves a sense of balance.
This model works because it respects both the reality of unequal earnings and the principle that both partners deserve discretionary money. It does require transparency about income, which some couples find uncomfortable. It also requires regular recalculation whenever income changes, which is easy to forget.
Model 3: Pool Everything
All income goes into one account, and all expenses come out of it. Each partner gets an agreed personal allowance, and the rest is shared. This is common among married couples and those who see their finances as fully merged.The strength of this model is simplicity and unity. There is no his money or her money, only our money. It can reduce scorekeeping and reinforce the idea that you are a team.
The risk is that it can mask inequality. If the higher earner controls spending decisions because they feel they earned the money, pooling does not fix that. It just hides it. Pooling works best when both partners genuinely see all income as joint property and when both have equal access and equal say.
Model 4: Hybrid Approach
Many couples combine elements. They pool money for shared fixed expenses like rent and utilities, keep separate accounts for personal spending, and maintain a joint savings account for goals like a home down payment or a vacation. This hybrid model gives structure without forcing full merging.The hybrid approach is often the most practical for couples with significant income differences because it separates the question of shared responsibility from the question of personal autonomy. You decide together what is shared, and you each keep control over what is not.
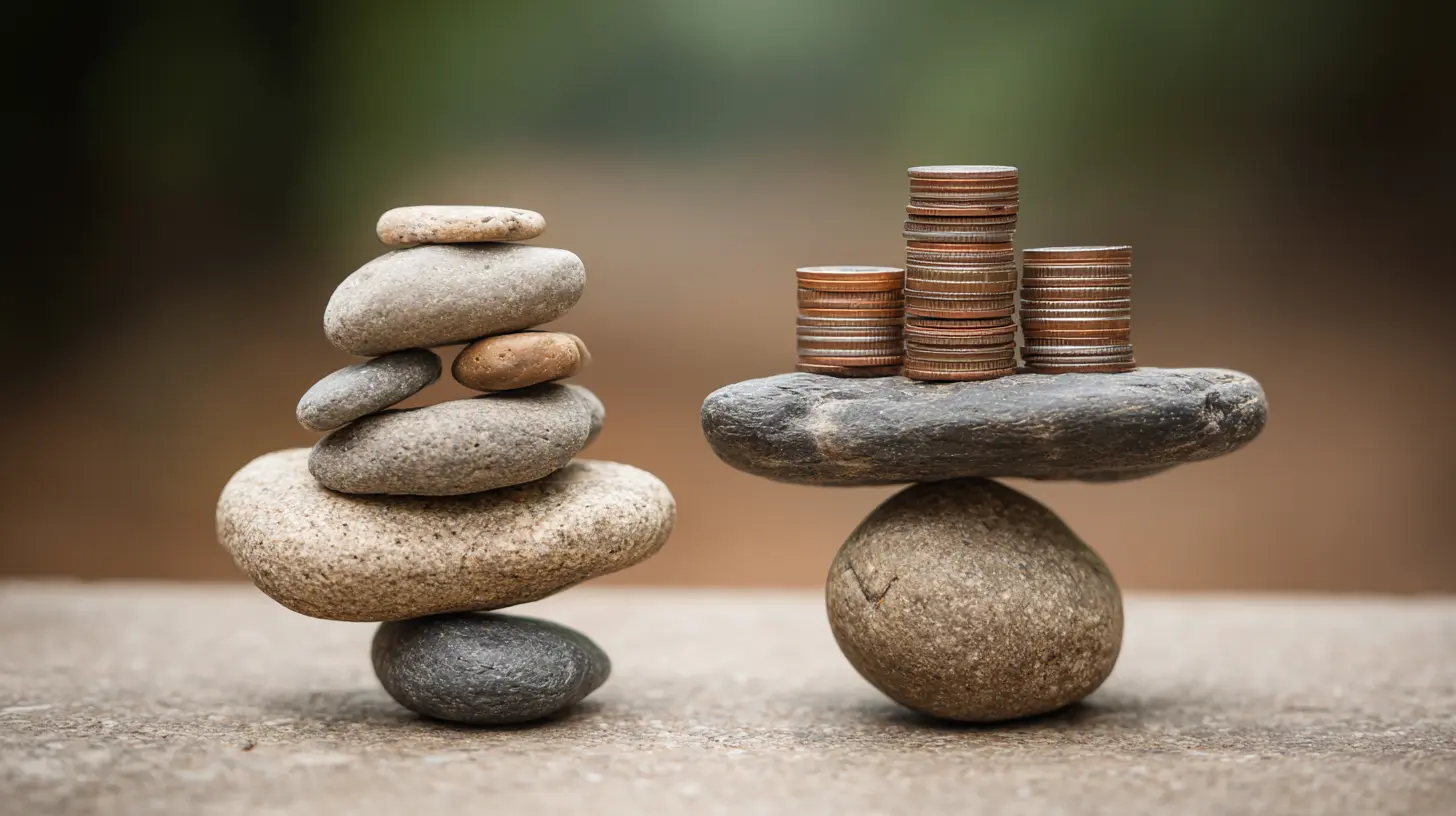
How to Choose the Right Model for Your Relationship
Choosing a model is less about math and more about answering a few honest questions.First, how different are your incomes? A small gap can tolerate a fifty fifty split. A large gap usually calls for proportional contributions or pooling.
Second, how do you feel about financial independence? Some people need their own account and their own spending money to feel secure. Others are comfortable with full merging. Neither preference is superior, but ignoring it creates friction.
Third, what is your legal status? Marriage, domestic partnership, and cohabitation carry different legal and financial implications. If you are not married, keeping some finances separate protects both partners in ways that pooling does not.
Fourth, how stable are your incomes? If one partner is a freelancer with variable income, a proportional model based on last year's earnings may not work. You might need a base contribution plus a true up at the end of the year.
Finally, how do you handle disagreement? If you cannot discuss money without arguing, start with a simpler model and revisit it once communication improves. Complexity amplifies conflict.
The Psychology of Being the Lower Earner
Being the partner who earns less comes with a specific set of emotional challenges that rarely get discussed openly.The lower earner often feels pressure to justify their spending in ways the higher earner does not. They may avoid asking for shared money even when it is legitimately theirs. They may overcompensate by taking on more household labor to feel they are contributing equally. Over time, this can lead to burnout and quiet resentment.
If you are the lower earner, it helps to remember that income is not the only contribution to a household. Managing the home, raising children, supporting a partner's career, and handling administrative tasks all have real value. That said, emotional reassurance alone does not pay bills. You need a structure that gives you access to shared resources and a clear voice in decisions.
One practical step is to agree on a personal spending allowance that both partners receive equally, regardless of income. If the household can afford 500 dollars per month for each person, both get 500 dollars. This removes the sense that one partner is asking permission while the other is granting it.
The Psychology of Being the Higher Earner
The higher earner faces a different set of pressures. They may feel that they carry an unfair burden, especially if they work long hours or a stressful job. They may resent funding a lifestyle they would not choose alone. They may also feel guilty for having those feelings, which makes it harder to talk about them.If you are the higher earner, it is worth examining what you actually want. Do you want your partner to contribute more? Do you want recognition for what you provide? Do you want more control over how shared money is spent? These are legitimate desires, and naming them is the first step toward addressing them.
It is also worth remembering that income differences are often temporary. A partner who earns less today may earn more in five years. A partner who is currently the breadwinner may step back to care for a parent or pursue a different career. Building a system that treats income as a shared resource, rather than a claim on power, protects both of you through these transitions.
Common Mistakes Couples Make
Certain patterns show up again and again when incomes are unequal. Recognizing them early can save years of frustration.Keeping Score
Tracking who paid for what, especially in small amounts, turns a partnership into a ledger. Scorekeeping often starts as a way to ensure fairness, but it usually ends in resentment. The fix is not to ignore fairness but to build a system that feels fair without constant tallying.Avoiding the Conversation
Many couples never explicitly discuss how they will handle unequal income. They default to whatever feels natural, which often means the higher earner pays more without any agreement. This works until it does not. A sudden job loss, a large purchase, or a change in priorities can expose the lack of a plan.Using Money as Leverage
If one partner says things like "I pay the mortgage, so I decide where we live," the relationship has a power problem, not a money problem. Money should not be a tool for control. If it is, couples counseling or financial therapy can help.Ignoring Retirement and Long Term Goals
When incomes are unequal, it is easy to focus on monthly bills and neglect long term planning. But retirement contributions, emergency funds, and insurance matter even more when one partner earns significantly less. The lower earner may have less access to employer retirement plans, which means the couple needs to plan deliberately for their future.Forgetting to Revisit the Arrangement
Income changes. Jobs change. Children arrive. A split that worked two years ago may be completely wrong today. Schedule a money check in every six months, even if it is just a thirty minute conversation.
Practical Steps to Build a Fair System
Here is a concrete process you can follow, whether you are starting from scratch or fixing a system that is not working.Step one. Gather the numbers. Write down each partner's after tax monthly income, all shared expenses, and all individual expenses. Do not guess. Use bank statements.
Step two. Define shared expenses. Rent or mortgage, utilities, groceries, insurance, transportation, and any debt payments that serve both partners. Be specific. Ambiguity is where conflict lives.
Step three. Choose a contribution method. Proportional is a strong default for most couples with unequal incomes. Fifty fifty works if the gap is small. Pooling works if you both genuinely want full merging.
Step four. Set personal allowances. Each partner gets the same amount of no questions asked spending money each month. This is not a luxury. It is a safeguard against resentment.
Step five. Automate. Set up automatic transfers on payday so the system runs without willpower. Automation reduces arguments because the decision was already made.
Step six. Review every six months. Adjust for income changes, new goals, and lessons learned.
When to Get Professional Help
Some situations benefit from outside expertise. If you and your partner cannot discuss money without fighting, a couples therapist who specializes in financial issues can help. If your finances are complex, with business income, investment properties, or significant debt, a fee only financial planner can design a structure that fits your situation. If you are unmarried and buying property together, a lawyer can help you draft an agreement that protects both parties.The cost of professional advice is often far less than the cost of a financial mistake or a relationship breakdown.
A Final Word on Fairness
Fairness in a relationship is not the same as equality. Equal contributions make sense when incomes are equal. When they are not, fairness means each partner contributes what they can, receives what they need, and has an equal voice in decisions. That is a harder standard to define, but it is the one that sustains a partnership over decades.The couples who thrive with unequal incomes are not the ones who found a perfect formula. They are the ones who talk openly, adjust often, and treat money as a shared tool rather than a source of leverage. That approach takes effort, but it is effort that pays off in trust, security, and a relationship that can weather whatever financial surprises come your way.
all images in this post were generated using AI tools
Category:
Couples FinanceAuthor:
Yasmin McGee