How to Handle Financial Infidelity in Relationships
5 October 2026
Money arguments are the third rail of marriage. Touch it carelessly and everything lights up. But there is a difference between a couple who fights about spending and a couple dealing with financial infidelity. One is a disagreement. The other is a breach of trust that can hollow out a relationship from the inside, often for years before anyone notices.
Financial infidelity is any act of hiding, lying about, or deliberately obscuring money matters from a partner who has a reasonable expectation of transparency. It is not just a secret credit card. It is the hidden gambling account, the loan given to a sibling that never gets mentioned, the cash stashed in a drawer, the side business whose income never appears in the household budget, or the slow accumulation of debt that only surfaces when a mortgage application gets denied.
If you are reading this because you suspect something, or because you just found out, or because you are the one carrying a secret, you are in the right place. This is not a morality lecture. It is a practical guide to understanding what happened, why it happened, and what you can realistically do next.
Why Financial Infidelity Hits Harder Than People Expect
When most people imagine betrayal in a relationship, they picture romantic infidelity. Financial infidelity is different in ways that make it uniquely corrosive.First, money is not just money. It is security, autonomy, status, and a proxy for how much you trust someone with your future. When a partner hides financial behavior, they are not just hiding a number. They are making a unilateral decision about the shared life you are building together. That is why the emotional reaction often feels disproportionate to the dollar amount. A hidden $200 purchase can trigger the same sense of violation as a hidden $20,000 debt, because the issue is not the money. It is the secrecy.
Second, financial infidelity is often invisible. Romantic affairs tend to leave traces that people eventually notice. Financial secrets can sit undisturbed for years inside a bank account, a filing cabinet, or a phone app. There is no dramatic reveal. Just a slow drip of concealed decisions.
Third, it compounds. A hidden credit card balance accrues interest. A secret loan affects your joint credit. A concealed business loss can wipe out savings you thought were safe. By the time the truth comes out, the damage is usually worse than it was at the start, which makes the conversation harder and the resentment deeper.
The Many Faces of Financial Infidelity
People tend to think of financial infidelity as one specific thing. In reality, it shows up in several forms, and each one carries a different emotional weight and a different path to repair.Hiding spending
This is the most common form. One partner buys things and conceals them, either by paying in cash, using a separate account, or having packages delivered to a work address. The purchases themselves may be small or large, but the pattern is what matters. If someone feels the need to hide routine spending, it usually signals a deeper fear of judgment or control.Hiding debt
A partner takes on credit card debt, personal loans, buy-now-pay-later balances, or medical debt and does not disclose it. This is often the most damaging form because debt has a life of its own. It grows, it affects credit scores, and it can block major life decisions like buying a home or refinancing a mortgage.Hiding income
This can be a side job, a cash business, freelance work, or a raise that never gets mentioned. Sometimes the motive is to preserve personal freedom. Sometimes it is to fund a hidden habit. Either way, hiding income skews the household financial picture and often means one partner is carrying more of the shared burden than they realize.Secret accounts and assets
A partner opens a bank account, brokerage account, or cryptocurrency wallet without telling the other person. This can be a precursor to something bigger, including preparation for separation, but it is not always. Some people open secret accounts because they grew up in a household where money was weaponized and they never learned to feel safe without a private cushion.Financial control
This is the darker end of the spectrum. One partner restricts the other's access to money, monitors their spending, demands receipts, or gives an allowance. This is a recognized form of financial abuse and often overlaps with other forms of domestic control. It is not a two-sided problem in the same way the others are, and it requires a different response.Concealing financial decisions
This includes co-signing a loan for a family member, making a large investment, lending money to a friend, or starting a business, all without telling a partner. The decision itself may be reasonable. The concealment is the betrayal.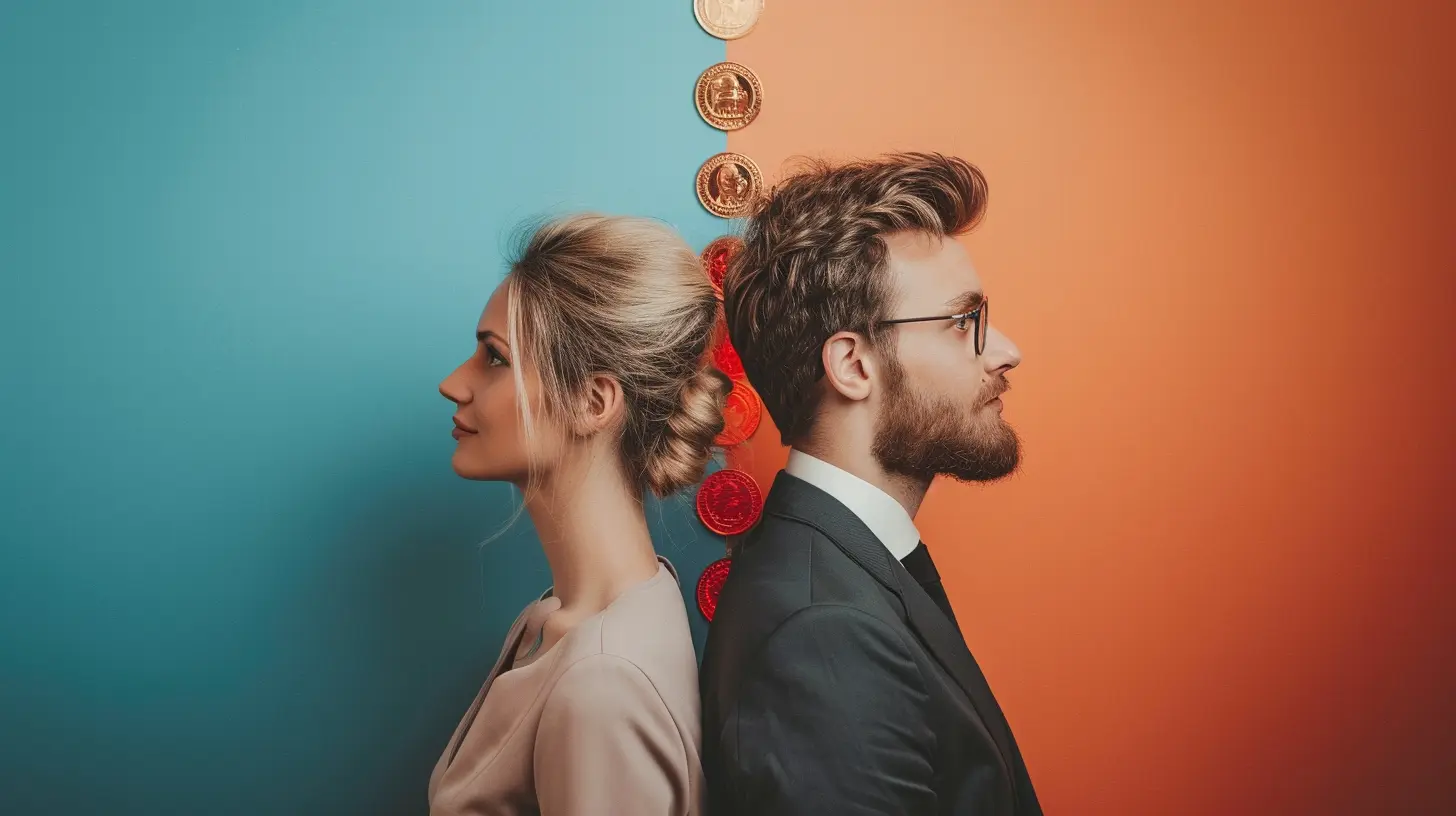
Why People Do It
If you have just found out that your partner has been hiding money, the instinct is to assume the worst. Sometimes that instinct is correct. Often it is not.Understanding motive matters because it shapes what repair looks like. A partner who hid spending because they were ashamed of a shopping habit needs a different response than a partner who hid assets because they were planning to leave.
Common drivers include:
Shame. People who grew up in households where money was tight often carry deep shame about spending, debt, or not earning enough. Hiding becomes a way to avoid that shame.
Fear of conflict. If every money conversation turns into a fight, a partner may decide it is easier to conceal than to argue. This is a coping mechanism, not a justification, but it is common.
Different money scripts. Two people can grow up with completely different relationships to money. One learns that saving is safety. The other learns that spending is freedom. When those scripts collide, secrecy can become a way to preserve autonomy.
Control. In some cases, hiding money is about power. One partner wants the freedom to make decisions without the other's input, and secrecy is how they protect that freedom.
Addiction. Gambling, drugs, alcohol, and compulsive shopping all drive financial secrecy. In these cases, the money problem is a symptom, and it will not resolve without addressing the underlying addiction.
Preparation for exit. Sometimes financial secrecy is a sign that a partner is planning to leave. This is painful to hear, but it is important to consider honestly, especially if the secrecy is combined with other signs of disengagement.
How to Tell the Difference Between a Mistake and a Pattern
One hidden purchase is not the same as five years of concealed debt. One forgotten conversation about a bonus is not the same as a secret second bank account.Ask yourself a few questions:
- Was this a one-time lapse or a recurring behavior?
- Did the person come forward, or did I find out by accident?
- When confronted, do they show genuine remorse or do they minimize and deflect?
- Is there a history of other kinds of dishonesty?
- Does the secrecy serve to protect them from my reaction, or to protect their own interests at my expense?
A single mistake, owned honestly, is usually workable. A pattern of deception, especially one that continues after being confronted, is a different situation entirely.
The First Conversation: What to Do and What to Avoid
The moment you find out is rarely the moment for a productive conversation. If you are angry, hurt, or in shock, you are not in a position to negotiate. Give yourself time to process before you sit down to talk.When you do talk, here are some principles that make the conversation more likely to go somewhere useful.
Lead with the impact, not the accusation. "I found the credit card statement and I feel like I do not know what is happening in our finances" lands differently than "You lied to me." Both may be true, but the first invites a response. The second invites a defense.
Ask open questions first. Before you explain how you feel, get the full picture. How long has this been going on? What else is there? Is this the only thing I do not know about? You cannot solve a problem you only half understand.
Avoid ultimatums in the first conversation. Ultimatums made in the heat of the moment are usually about discharging emotion, not about setting boundaries. If you need to set a boundary, do it later, when you are calm and can follow through.
Do not accept "it was no big deal." Minimizing is a common response, but it is not a resolution. If your partner cannot acknowledge that the secrecy itself was the problem, you have not yet reached the starting line.
Take notes. This sounds cold, but in the days and weeks after a disclosure, details blur. Writing down what you learned, what was promised, and what you still do not know will help you keep track.
Rebuilding Trust: A Realistic Timeline
Trust is not rebuilt in a single conversation. It is rebuilt through consistent behavior over time. That timeline is usually measured in months, not weeks, and sometimes in years.There is no shortcut. But there are things that make the process more likely to succeed.
Full disclosure
The hiding partner needs to come completely clean. Not just about the specific thing you found, but about everything. Partial disclosures that trickle out over months are more damaging than a single painful reckoning, because each new revelation resets the clock on trust.Access and transparency
For a period of time, the hiding partner should expect less privacy around money. Shared accounts, shared statements, shared access to financial apps. This is not punishment. It is the equivalent of a partner who had an affair sharing their phone location for a while. It is a temporary scaffolding that makes rebuilding possible.A joint financial picture
Both partners need to sit down and build a complete picture of the household finances. Assets, debts, income, obligations, credit scores, tax situation. Everything. This is uncomfortable, especially if one partner has been avoiding the numbers. But you cannot make joint decisions from a place of partial information.Regular check-ins
Schedule a monthly money meeting. It can be 30 minutes. The point is not to scrutinize every purchase. The point is to normalize transparency and catch problems early. Couples who talk about money regularly are far less likely to drift into secrecy.Professional help
A financial therapist, a couples counselor, or a fee-only financial planner can all play a role. A financial therapist addresses the emotional patterns behind the secrecy. A planner helps you rebuild the actual financial plan. A couples counselor helps with communication. You may need more than one.When the Hiding Partner Is You
If you are the one who has been hiding money, this section is for you. Read it carefully, because the way you respond in the next few weeks will shape whether your relationship survives.Tell the whole truth. Not the version that makes you look least bad. The whole thing. If you trickle it out, you will destroy whatever trust remains.
Do not blame your partner. Even if their reaction to past money conversations made secrecy easier, the decision to hide was yours. Own it without deflecting.
Expect anger and give it room. Your partner is allowed to be furious. They are allowed to grieve. Do not rush them toward forgiveness because you are uncomfortable with their pain.
Change the behavior, not just the apology. Apologies are cheap. What matters is whether the secrecy stops. That means opening accounts, sharing access, and accepting oversight for a period of time.
Get help for the underlying issue. If the secrecy was driven by addiction, shame, or a trauma history, a financial planner alone will not fix it. Therapy is not optional in these cases.
When Repair Is Not Possible
Not every relationship survives financial infidelity. Some should not.If the secrecy was part of a broader pattern of control, manipulation, or abuse, the right move is usually to leave, and to leave with professional support. Financial abuse is a recognized form of domestic violence, and there are organizations that help people safely extricate themselves from financially controlling relationships.
If the hiding partner refuses to disclose fully, continues to lie after being confronted, or blames you for their behavior, you are not dealing with a mistake. You are dealing with a character pattern. That is a much harder thing to change.
If you have children, the calculus gets more complicated, but it does not change the fundamentals. Children do better in two healthy households than in one unhealthy one.
Preventing Financial Infidelity Before It Starts
The best time to prevent financial infidelity is before it happens. A few habits make it far less likely.Talk about money early and often. Not just budgets, but values. What does money mean to you? What did you learn about it growing up? What are you afraid of? These conversations build the trust that makes secrecy unnecessary.
Decide together what "ours" and "yours" means. Some couples pool everything. Some keep separate accounts and contribute to a joint one. Some do a hybrid. There is no single right answer, but there is a right answer for your relationship, and you need to agree on it explicitly rather than assume.
Set a disclosure threshold. Agree on a dollar amount above which purchases or financial decisions get discussed. It could be $100 or $1,000. The number matters less than the agreement.
Review finances together monthly. Twenty minutes a month prevents most surprises.
Normalize mistakes. If a partner is terrified of your reaction to a small money mistake, they are more likely to hide the next one. Create a culture where mistakes are discussable.
A Final Word
Financial infidelity is not a small thing, and it is not a moral failing unique to bad people. It is a behavior that grows out of fear, shame, avoidance, and sometimes something darker. The way through it is not denial and it is not a single dramatic confrontation. It is honesty, structure, and time.If you are in the middle of this right now, know that the pain is real and the confusion is normal. You do not have to decide today whether the relationship survives. You only have to decide what the next honest step is. Take that step, and then the next one. That is how trust gets rebuilt, one transparent decision at a time.
all images in this post were generated using AI tools
Category:
Couples FinanceAuthor:
Yasmin McGee
Discussion
rate this article
1 comments
Ethan Thornton
Trust is fragile; rebuild with honesty.
October 5, 2026 at 4:05 AM